Business succession planning with Wills and LPAs

Last verified: October 2026 (England & Wales)
If you were suddenly unable to make decisions, who could deal with your business interests? If you died, would your family inherit what you intended?
A Will sets out who benefits from your estate after death. A Property and Financial Affairs Lasting Power of Attorney (LPA) allows chosen people to act for you during your lifetime, within the authority you give them. For a business owner, both documents should fit how the business is owned and run.
Fern helps with the Will, LPA and family-inheritance parts of that planning. Company management, partnership arrangements, insurance and specialist tax advice involve other advisers. Bringing those parts together can reduce avoidable uncertainty for your family and the people who depend on the business.
The main points
- Plan for inheritance and lifetime decision-making separately. A Will and an LPA do different jobs.
- Owning shares, managing a company and acting as an attorney are different roles.
- Separate personal and business LPAs can be useful where different people should act, but are not necessary for every owner.
- Confirm the important business arrangements with the appropriate adviser so your Will and LPA planning can take account of them.
What happens if you cannot deal with the business
An unexpected illness can leave a business waiting for decisions about payments, contracts or its future. The practical question is whether someone else has suitable authority and knows what matters most.
Being in hospital, travelling or physically unable to attend a meeting does not automatically mean losing mental capacity. Capacity concerns your ability to make a particular decision when it is needed. A financial LPA can allow help with your permission while you retain capacity, once registered and if its terms allow. It can also provide authority if you later lose the relevant capacity.
An LPA must be made while you have capacity to make it and registered before use. After death, the attorney’s authority ends and responsibility for your estate passes to your personal representatives. Company management remains subject to the company’s own arrangements.
The six parts of a practical plan
1 Your Will
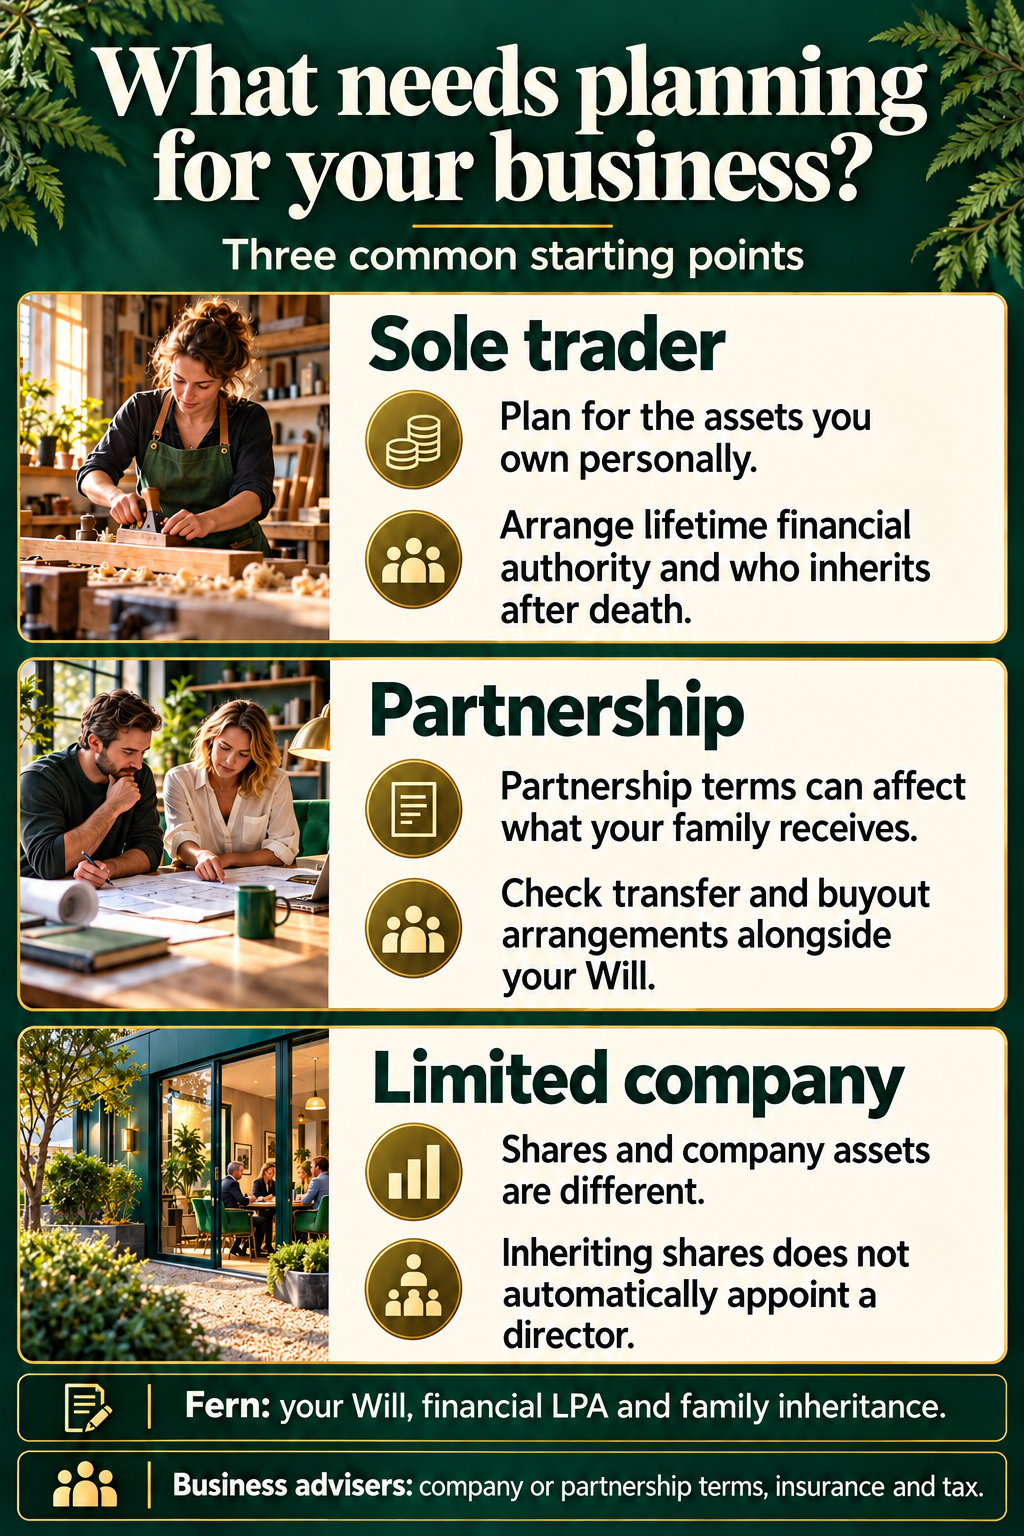
Start with what you personally own: perhaps company shares, a partnership interest or assets used in a sole-trader business. A company’s own money and property are separate from its shareholders’ estates.
Your Will can identify who should inherit and appoint executors to deal with your estate. It should take account of confirmed transfer restrictions or buyout arrangements. Sometimes family members inherit an ownership interest; sometimes they receive money following a sale.
You will not usually need a separate business Will in England and Wales. The aim is to deal properly with your business interests alongside the rest of your estate.
2 The business arrangements
Articles of Association set rules for a company. A shareholders’ agreement may add rights or obligations between its owners. Partnerships have their own arrangements. These can affect transfers, valuations, buyouts and who can make decisions.
Your Will cannot remove those obligations simply by naming a beneficiary. Ask the commercial solicitor or other appropriate adviser responsible for the arrangement to confirm its effect. Fern can then use the relevant confirmed information in the agreed estate-planning work.
3 A business focused LPA
A Business or Commercial LPA is a Property and Financial Affairs LPA limited to business matters. It uses the ordinary financial LPA form. The wording and choice of attorneys should reflect the decisions someone might need to make for you.
Separate personal and business LPAs can appoint people with different skills. Their boundaries must be clear and compatible. An existing financial LPA should be considered before deciding whether another document or a replacement is appropriate.
Choose someone with the judgement, availability and relevant experience to act for you. An attorney does not automatically become a company director or gain access to every company account. Company authority, partnership terms and bank mandates still need to be addressed through the appropriate business arrangements.
4 A Letter of Wishes
A Letter of Wishes gives your executors, trustees or attorneys useful context. It might explain a preference for family involvement, an orderly sale, or consultation with particular advisers.
It is guidance, not a binding instruction. It cannot change your Will, extend an LPA or override legal duties. Keep business wishes realistic and distinguish what you hope will happen from what the appointed person can lawfully decide.
5 A General Power of Attorney
A General or Ordinary Power of Attorney can help with financial matters while you retain mental capacity, for example during travel, recovery from an operation or a particular transaction. Its scope must fit the task.
It stops being authority if you lose the relevant mental capacity, so it cannot replace an LPA for that risk. Our guide to the different types of Power of Attorney explains the distinction.
6 How your family inherits
An outright gift will suit some families. In other circumstances, an ordinary Will trust may help protect a beneficiary or allow trustees to decide when support is provided. A trust means that trustees hold and manage money or property for the people or purposes specified in the Will.
That discussion can include your business interests or money your estate receives from their sale, where suitable. The choice depends on your family, the assets and any restrictions. A trust holding shares does not itself give the trustees authority to manage the company.
Trustees take on responsibilities, and ongoing tax, administration or professional costs may arise. After death, executors and trustees must bring the trust into operation. Fern prepares suitable Will trusts but does not take trustee appointments, create standalone lifetime trusts or register trusts. We can introduce an appropriate specialist for implementation or administration; you remain free to choose your own adviser.
Who can act and in which role
The same person may hold more than one role, but each has its own source of authority.
| Role | What it covers |
| Executor | Your estate after death, including business interests you owned. This does not automatically appoint the executor as a director. |
| Company director | Management of the company under company law and its governing arrangements. |
| LPA attorney | Your decisions within the registered LPA’s authority. Your personal appointment does not itself confer a company office. |
| General attorney | The financial authority granted while you retain the relevant mental capacity. |
| Trustee | The trust assets and beneficiaries under the trust terms and legal duties. |
| Co-owner or shareholder | The rights attached to their ownership, including relevant agreement and company rights. |
What to discuss with Fern first
A useful first conversation starts with your circumstances and intended outcome. Tell us:
- How the business is owned, your role and who else is involved.
- Who you would like to benefit, and whether you favour family involvement, a buyout or a sale.
- Whether you already have a Will or LPAs, and who is appointed.
- Whether company, partnership, buyout or insurance arrangements exist, what you understand them to achieve, and who advises on them.
You do not have to interpret professional documents yourself. If a point is uncertain, with your specific authority we can seek confirmation from the relevant adviser. We will ask for particular documents where their wording is needed for the agreed work or a conflict needs resolving. Any material extra review and fee will be agreed first.
Questions for your business advisers
Your commercial solicitor, accountant or regulated financial or insurance adviser can confirm the matters within their respective roles. Useful questions include:
- What happens to my ownership interest on death, and do other owners have purchase or transfer rights?
- How would a buyout be valued and funded, and does any insurance support that arrangement?
- Who could make management decisions and authorise payments if I could not act?
- Do professional qualifications or regulatory rules restrict ownership or management?
- What tax consequences should be considered before the plan is settled?
Receiving the financial value of a business and running it are different outcomes. This matters particularly where family members are not involved, children have different interests, or professional rules restrict who can manage the work.
Examples of the planning issues
When one person authorises everything
A small engineering firm relied on one owner to approve payments and key contracts. A sudden hospital admission put payroll and supplier arrangements under pressure. The lesson is to consider the owner’s financial authority alongside company signing and management arrangements. An LPA on its own cannot resolve every dependency.
When the family expects shares but a buyout is intended
An owner left shares to a spouse, but the company documents gave the surviving co-owner the first option to buy them. The family expected control; the co-owner expected a purchase. In a similar matter, we introduced a financial adviser to arrange life cover for the intended transfer. The Will, purchase arrangements and funding each had a separate job.
When the beneficiary cannot run the practice
The owner of a professional practice wanted to provide for a spouse who did not have the background or appetite to run the firm. Planning focused on financial provision and suitable management or sale arrangements. In a regulated business, inheriting value does not establish eligibility to carry on its work.
When a partnership relies on assumptions
Two partners assumed the other could carry on if one became unwell. When one could not engage for several months, the bank sought clear authority for certain instructions and a mandate change. Trading slowed. Discussing the agreement, bank arrangements and suitable personal authority in advance can expose gaps while there is still time to address them.
When family relationships obstruct decisions
In a family-business matter, we used a General Power of Attorney while the owner retained capacity so an experienced accountant could represent his interests. This helped communication while a longer-term solution was addressed. The authority was limited to its terms; it did not automatically transfer a director’s office or settle the underlying dispute.
When a future sale is the preferred outcome
A consultancy owner reviewed their Will alongside the company documents, made a business focused LPA and clarified banking authority. Decisions continued when incapacity later occurred, and the business was sold in an orderly way after death. The planning helped the family, but a sale’s price and timing always depend on the business, market and circumstances.
When to review your arrangements
Review them when ownership changes, someone important joins or leaves, family circumstances change, or the business begins to depend heavily on one person. A new agreement, borrowing arrangement or planned sale may also affect the estate plan.
If you already have a financial LPA, start by considering its scope and attorneys. Adding a business LPA does not automatically cancel the existing one. Where replacement is appropriate, revocation and the transition between documents need to be handled deliberately.
Bank access can be delayed or restricted while authority is established. Registration alone does not mean an attorney can immediately operate every account. The account ownership, mandate, LPA terms and bank’s checks all matter.
If you are considering treating the cost as a business expense, ask your accountant about the particular work and business structure. A connection with business continuity does not by itself establish the tax treatment.
Take the next step
You have put time and effort into your business. Planning who can act and how your family benefits helps protect that work when circumstances change.
Contact Fern Wills & LPAs to discuss your Will and LPA arrangements. We will identify the estate-planning work we can provide and the points that require confirmation from your business advisers. You can see the services available on our Services & Fees page.
This article is general information only, not individual advice.