Vulnerable Person Trusts (VPT)
If someone you love may struggle to manage an inheritance safely, you do not have to choose between leaving them money outright and leaving them out.
A Vulnerable Person Trust allows you to include a vulnerable or disabled loved one in your Will while placing their inheritance under the care of trustees you choose. Those trustees can use the fund for the person’s support, safety, independence and quality of life without handing them a lump sum to manage alone.
Because the inheritance is held by trustees rather than owned outright, a properly structured VPT can substantially reduce the risk that an inheritance disrupts means-tested support. It can also protect the fund from pressure, exploitation, impulsive spending or decisions the beneficiary may find difficult to make safely.
A VPT lets you say “yes, they are included” while giving their inheritance the protection and management it needs.
A VPT is also sometimes called a Disabled Person’s Trust. Where the beneficiary and trust meet the statutory conditions, special tax treatment may be available.
Quick-read summary
A Vulnerable Person Trust:
- Protects an inheritance for a vulnerable or disabled person.
- Places trusted people in control of how the inheritance is managed.
- Allows trustees to pay for care, accommodation, equipment, activities and other things that improve the person’s life.
- Can substantially reduce the risk of means-tested support being disrupted by an outright inheritance.
- Helps protect the fund from misuse, pressure or unsafe spending.
- May qualify for favourable tax treatment where the legal conditions and required elections are met.
- Is usually written into a Will and starts when assets pass into it after death.
Protect the inheritance. Empower the trustees. Support the person.
Why Families choose a VPT
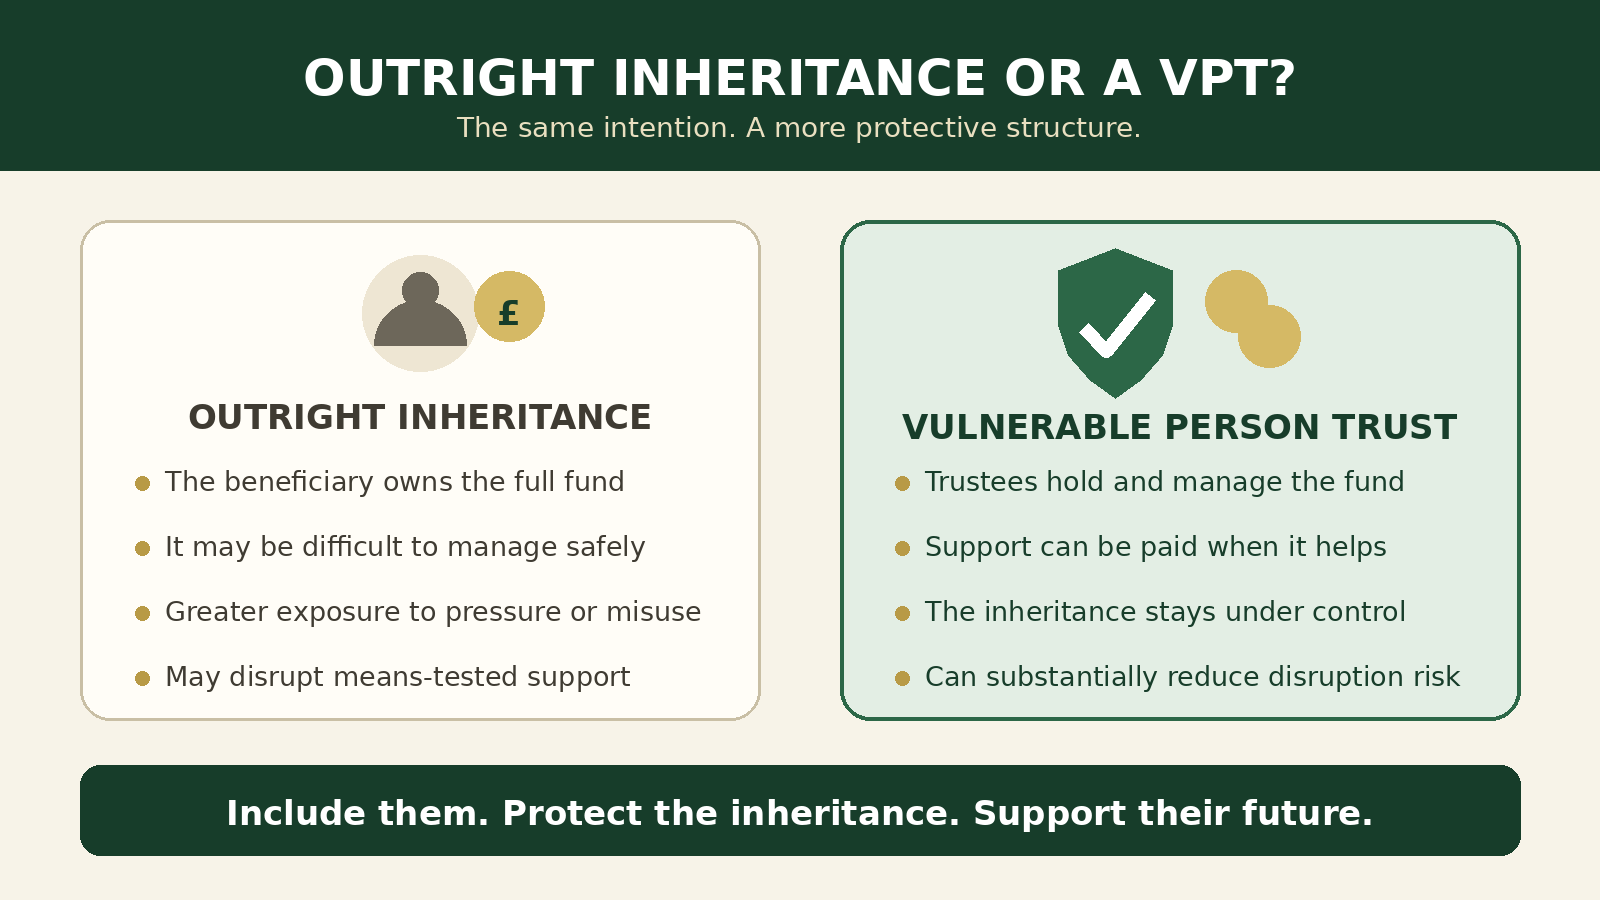
Leaving an inheritance outright can expose it to unsafe management, pressure from other people or disruption to means-tested support. Leaving the person out provides them with no benefit from the estate. A Vulnerable Person Trust offers a more constructive middle course: your loved one remains included, while trusted people manage the inheritance and use it to improve their life.
VPT or ordinary Discretionary Trust?
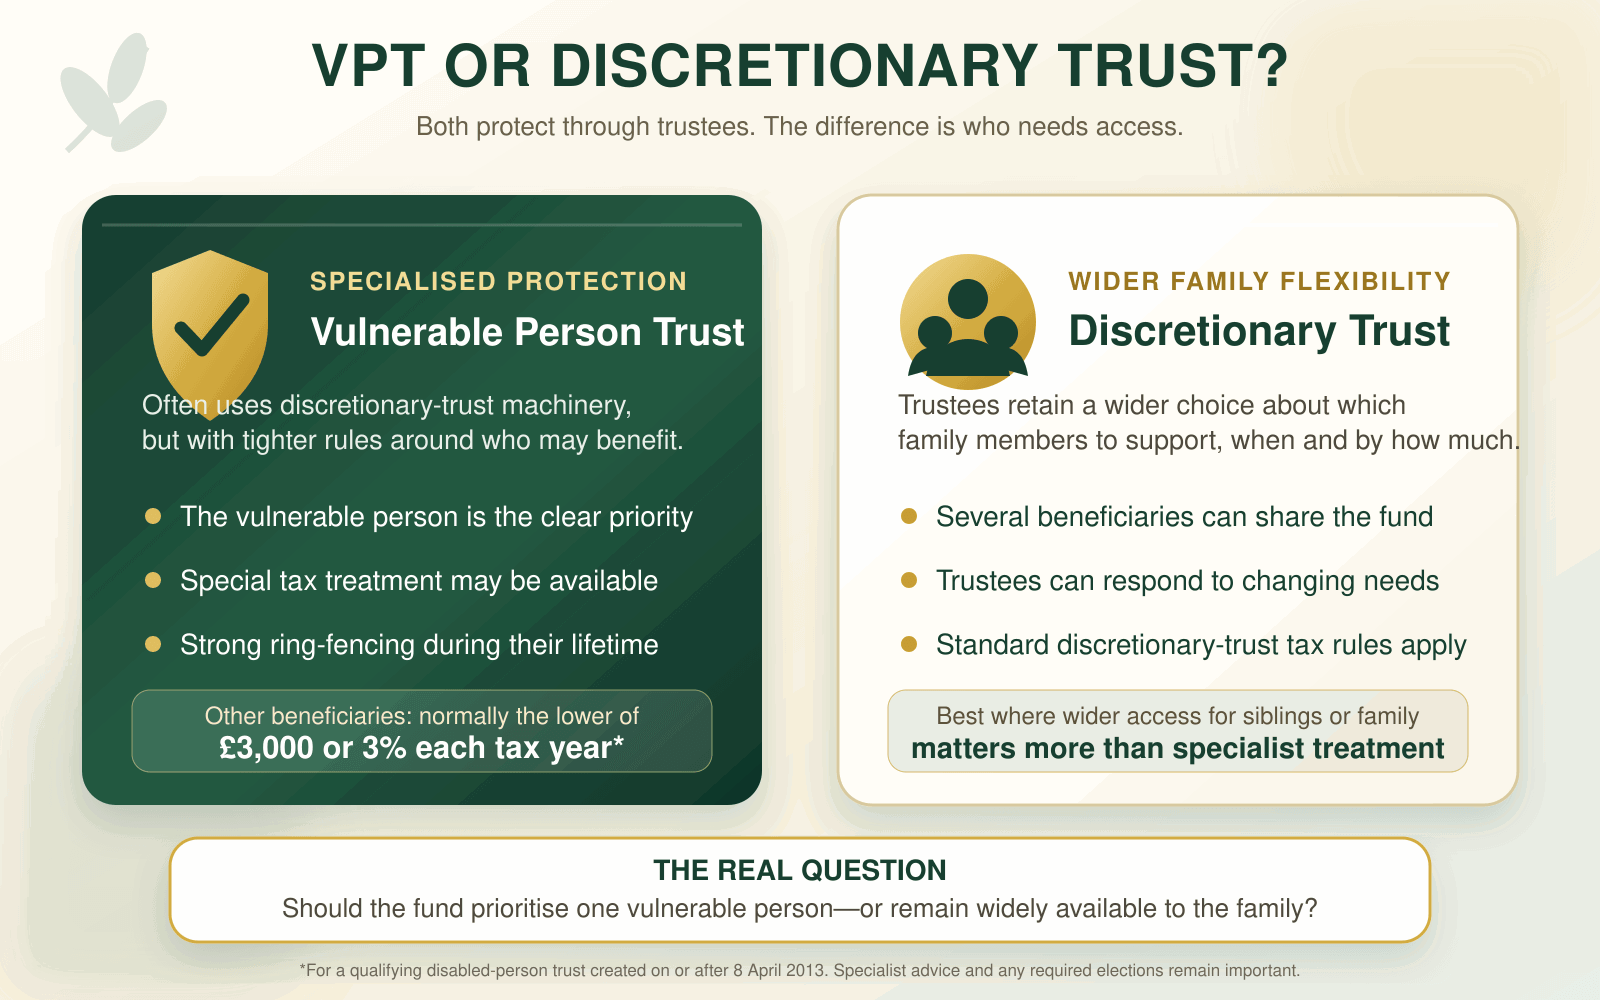
Both structures can prevent a vulnerable person from receiving their inheritance as an unprotected lump sum. The important difference is how tightly the money is centred on that person.
A Vulnerable Person Trust is often built using discretionary-trust powers, but with tighter rules so that one qualifying vulnerable or disabled person remains the clear priority. Where the statutory conditions and elections are satisfied, special tax treatment may also be available.
That tighter protection limits how freely the trustees can benefit other people while the vulnerable person is alive. For a qualifying trust established on or after 8 April 2013, the total that can normally be used for everyone else is limited to the lower of £3,000 or 3% of the trust fund in each tax year. This is one combined limit across the other beneficiaries, not a separate allowance for each brother or sister.
The restriction helps preserve the trust’s specialist protection. It does not prevent brothers, sisters or other chosen beneficiaries from receiving what remains after the vulnerable person dies.
An ordinary Discretionary Trust can still keep the inheritance under trustee control and protect against an immediate lump-sum inheritance. A Letter of Wishes can tell the trustees to treat the vulnerable person as the practical priority. However, the trustees usually have greater freedom to help other family members during the vulnerable person’s lifetime.
For many families, the decision therefore comes down to the main purpose:
- Choose a VPT where the strongest specialist protection centred on one vulnerable person is the priority.
- Consider an ordinary Discretionary Trust where wider access and flexibility for several family members is more important.
The choice is not between protection and no protection. It is between specialist protection centred on one vulnerable person and wider flexibility for the family.
Related reading: Discretionary Trusts – Flexibility and Peace of Mind
How a VPT works
The trust provisions are included in your Will.
When the relevant inheritance becomes payable:
- The beneficiary’s share passes into the trust rather than to them personally.
- The trustees take control of the trust fund.
- The trustees keep the trust assets separate and manage them responsibly.
- They use the fund for the beneficiary in accordance with the Will and their trustee duties.
- They obtain specialist benefits, tax, investment or legal advice when a significant decision calls for it.
The trustees act as careful gatekeepers. They can provide support when it is needed while protecting the fund for the longer term.
What can trustees pay for?
Depending on the person’s needs and the terms of the trust, trustees may be able to fund:
- Care, support or accommodation costs.
- Therapies, equipment and adaptations.
- Education, training and independence support.
- Clubs, hobbies and social activities.
- Holidays, travel and family experiences.
- Technology, furniture and personal items.
- Professional support and advocacy.
- Other expenses that genuinely improve the beneficiary’s life.
Trustees can often pay a provider directly instead of handing over cash.
The exact payment method matters where means-tested support is involved, so trustees should check the current position before making substantial or unusual payments.
The trust is there to improve the beneficiary’s life, not simply to preserve money.
Who might benefit from this planning?
A VPT may be worth considering where the intended beneficiary:
- Has learning difficulties or a learning disability.
- Has a physical disability.
- Experiences serious or fluctuating mental-health difficulties.
- Receives means-tested benefits or local-authority support.
- Is vulnerable to financial pressure, exploitation or impulsive spending.
- Cannot manage substantial assets safely.
- Needs support that is likely to continue after parents or carers have died.
The word “vulnerable” is used broadly in everyday conversation. The legal test for special vulnerable-beneficiary tax treatment is narrower.
A protective trust may still be appropriate even if the beneficiary does not qualify for the special tax treatment.
Why a Will-based VPT is usually the starting point
For most families, the simplest approach is to include the trust in their Wills.
This means:
- The trust is ready if it is needed.
- The inheritance passes directly into the protective structure.
- There is normally no separate trust administration merely because the clause exists in the Will.
- The practical administration begins only when assets actually pass into the trust.
- Costs remain proportionate while the Will-makers are alive.
Lifetime trusts can be appropriate where money needs to be transferred during someone’s lifetime, but they require specialist advice and may bring forward registration, tax and administrative responsibilities.
Fern creates VPT provisions that arise through Wills. Where a separate lifetime structure is being considered, we can introduce suitable specialist support.
Protecting means-tested support
A direct inheritance may be taken into account when a person’s entitlement to means-tested support is assessed.
A VPT offers a more protective alternative because the trustees, rather than the beneficiary, own and control the trust fund. Trustees can then use the money for the beneficiary without simply transferring the whole inheritance to them.
This can substantially reduce the risk of an inheritance disrupting means-tested support, particularly where:
- The trust has been drafted appropriately.
- The beneficiary does not have an absolute right to demand the fund.
- Trustees make careful payment decisions.
- Trust money is kept separate.
- Current benefits rules are considered before significant payments.
Benefits decisions remain dependent on the person’s circumstances, the trust terms, the payments made and the rules in force at the time. No adviser or trust can guarantee how an authority will decide a future case.
That does not remove the value of the planning. It explains why careful drafting, suitable trustees and current advice are important.
Where benefit disruption is a concern, a properly drafted and carefully managed VPT is generally a safer route than leaving the inheritance outright.
Special tax treatment
Where the beneficiary and trust meet the statutory conditions, a VPT may qualify for special treatment for:
- Income Tax.
- Capital Gains Tax.
- Inheritance Tax.
The trustees and beneficiary may need to make a vulnerable-person election and claim the relevant treatment. The exact position depends on the beneficiary, the trust terms, the assets and how the trust is operated.
Tax qualification and benefits treatment are separate questions. A trust can be useful for protection and management even where the special vulnerable-beneficiary tax treatment is unavailable.
Fern identifies the planning issues and drafts the Will trust. Where elections, calculations, returns or specialist tax advice are required, we can introduce an appropriate professional.
Choosing the trustees
The trustees will control and manage the inheritance, so choosing the right people is essential.
Good trustees should:
- Understand the beneficiary and their support needs.
- Be responsible and organised with money.
- Be willing to ask for professional help.
- Work constructively with other trustees and family members.
- Make decisions for the beneficiary’s benefit.
- Be able to resist pressure from the beneficiary or other people where necessary.
- Keep proper records and explain their decisions.
Trustees are often siblings, relatives or trusted friends. Professional assistance can be introduced where the fund, investments, tax position or family circumstances justify it.
Your Letter of Wishes
A Letter of Wishes sits alongside the Will and gives the trustees practical guidance.
It can explain:
- What good support looks like for your loved one.
- Their routines, preferences and communication needs.
- The activities and experiences that matter to them.
- Your priorities for accommodation, care and independence.
- Any financial, personal or safeguarding concerns.
- How you would like trustees to work with family members and professionals.
The Letter of Wishes is not normally legally binding, which allows it to remain flexible. Nevertheless, it can be one of the trustees’ most valuable sources of guidance.
Long-term family flexibility
Typically, the vulnerable or disabled person is the principal beneficiary during their lifetime.
Other family members may be named as back-up beneficiaries so that any money remaining after the vulnerable person’s death can pass to them or continue under another suitable arrangement.
Where more than one vulnerable person needs protection, separate trusts may be preferable so that each fund can be managed around that person’s circumstances.
If other people are intended to benefit while the vulnerable beneficiary is alive, the trust must be structured carefully. Payments for other beneficiaries can affect access to special tax treatment.
Where wider family flexibility is the main objective, an ordinary Discretionary Trust may be more appropriate.
A VPT and the wider plan
A VPT protects an inheritance. It does not give parents or relatives authority to make health, care or financial decisions for an adult during their lifetime.
Where the person has sufficient understanding to make one, a Lasting Power of Attorney may complement the trust by appointing people to help with financial or welfare decisions.
Capacity is decision-specific and time-specific. A person with learning difficulties, a disability or fluctuating capacity should not automatically be assumed unable to make an LPA.
If an LPA cannot be made, other routes such as benefits appointeeship or deputyship may need to be considered.
Related reading: Lasting Powers of Attorney
Costs and practical administration
A Will-based VPT is designed to keep costs proportionate.
Many quiet years may involve little or no paid specialist work. Trustees may need professional assistance when there is:
- Trust Registration Service work.
- A tax return or vulnerable-person election.
- A significant investment decision.
- A substantial or unusual payment.
- A change in the beneficiary’s benefits or circumstances.
- A disagreement or difficult trustee decision.
Trustees can bring in specialist help when it adds value rather than treating every year as equally complicated.
Related reading: How much does a Will trust cost to set up and run?
Examples
An adult son with learning difficulties
Mark and Helen have an adult son, Daniel, who has learning difficulties and receives means-tested support.
They do not want to disinherit him, but they are concerned that leaving his share outright would give him more money than he could safely manage and could affect his support.
Their Wills direct Daniel’s inheritance into a VPT. The trustees can pay for supported activities, travel, equipment and other things that improve his quality of life while keeping the inheritance under responsible control. They obtain benefits advice before making substantial payments.
A daughter with fluctuating mental health
A mother wants to provide for her adult daughter, who experiences long periods of stability followed by serious mental-health relapses.
A VPT allows the trustees to respond to changing circumstances. They can pay providers directly, fund counselling or practical support and protect the remaining fund during periods when giving the daughter a lump sum would be unsafe.
Siblings acting as trustees
Grandparents include a VPT in their Wills for an autistic grandson.
His older sisters act as trustees. A detailed Letter of Wishes explains his communication needs, routines and interests. The trustees use the fund for specialist equipment, suitable activities and support that increases his independence.
The structure keeps decisions transparent and focused on his needs.
Does a VPT guarantee that benefits will be protected?
No trust can guarantee a future benefits decision. A properly structured VPT can, however, substantially reduce the risk created by an outright inheritance. Careful trustee decisions and current advice help keep that protection effective.
Is a VPT only worthwhile if special tax treatment applies?
No. The protective management and benefits-related advantages may still be valuable even if the beneficiary does not meet the separate tax qualification rules.
Can the beneficiary receive money directly?
Trustees may be able to make direct payments, but they should consider whether paying a provider or purchasing an item directly would better protect the beneficiary and their support.
Can siblings inherit what is left?
Usually, yes. Back-up beneficiaries can be included, although the trust wording and any payments during the vulnerable person’s lifetime must be considered carefully if special tax treatment is intended.
Does the trust restrict the beneficiary’s life?
It should do the opposite. The purpose is to provide structured access to money for support, opportunities and quality of life while protecting the person from the risks of managing the whole inheritance alone.
Who registers and administers the trust?
After assets pass into the VPT, the trustees are responsible for operating it and obtaining the necessary professional help. Fern does not register or administer trusts, but we can introduce appropriate specialists.
How Fern can help
Fern can:
- Discuss your family’s circumstances and what you want the inheritance to achieve.
- Explain whether a VPT or another Will structure appears most suitable.
- Help you choose trustees and back-up beneficiaries.
- Draft the VPT provisions within your Will.
- Prepare a practical Letter of Wishes with you.
- Identify issues that require specialist benefits or tax advice.
- Introduce appropriate professional support where needed.
Fern does not act as trustee, calculate tax or benefits entitlement, make tax elections, register trusts or provide ongoing trust administration.
Take the next step
If leaving an inheritance outright feels unsafe, doing nothing or excluding your loved one need not be the answer.
A Vulnerable Person Trust can turn an inheritance into a protected, flexible resource that trusted people use to support the life you want for them.
Ask Fern whether a Vulnerable Person Trust should be included in your Will.
Download the Vulnerable Person Trust one-page guide.
This article provides general information for England and Wales. It is not individual legal, tax or benefits advice.


