Flexible Life Interest Trust (FLIT)
Last verified: November 2026 (England and Wales)
You want your partner to be comfortable after your death, but you also want something left for the children. What happens if your partner remarries, needs extra support or has to make difficult decisions about money?
A Flexible Life Interest Trust, usually called a FLIT, can help you plan for those changes. It is written into your Will and combines a right for someone to benefit from your assets with powers for trustees to help the family as circumstances develop.
Its main attraction is flexibility. That flexibility also brings responsibilities, costs and possible inheritance-tax consequences, particularly for the extra allowance linked to leaving a home to descendants.
At a glance
- Your chosen person can receive trust income and, where the Will provides, live in the home.
- Trustees manage the assets and may be able to release capital or make loans under the Will’s powers.
- Assets remaining in the trust follow its terms, rather than the survivor’s own Will.
- Children’s eventual inheritance can change if trustees use capital to support other beneficiaries.
- The trust needs active administration, and it does not automatically save tax or protect assets from every claim.
Married, civil partners or unmarried?
This distinction matters from the start. A qualifying life interest for a spouse or civil partner normally benefits from inheritance-tax spouse exemption. Exceptions can apply, particularly where the couple have different long-term UK residence positions.
An unmarried partner does not have the same exemption, and unused inheritance-tax allowances cannot transfer between unmarried partners. Putting assets into a FLIT for a partner can therefore have a different tax outcome from doing so for a spouse.
The person receiving the immediate right to income or occupation is the first beneficiary for these purposes. Naming children to benefit later does not make them the immediate beneficiaries.
How a FLIT works
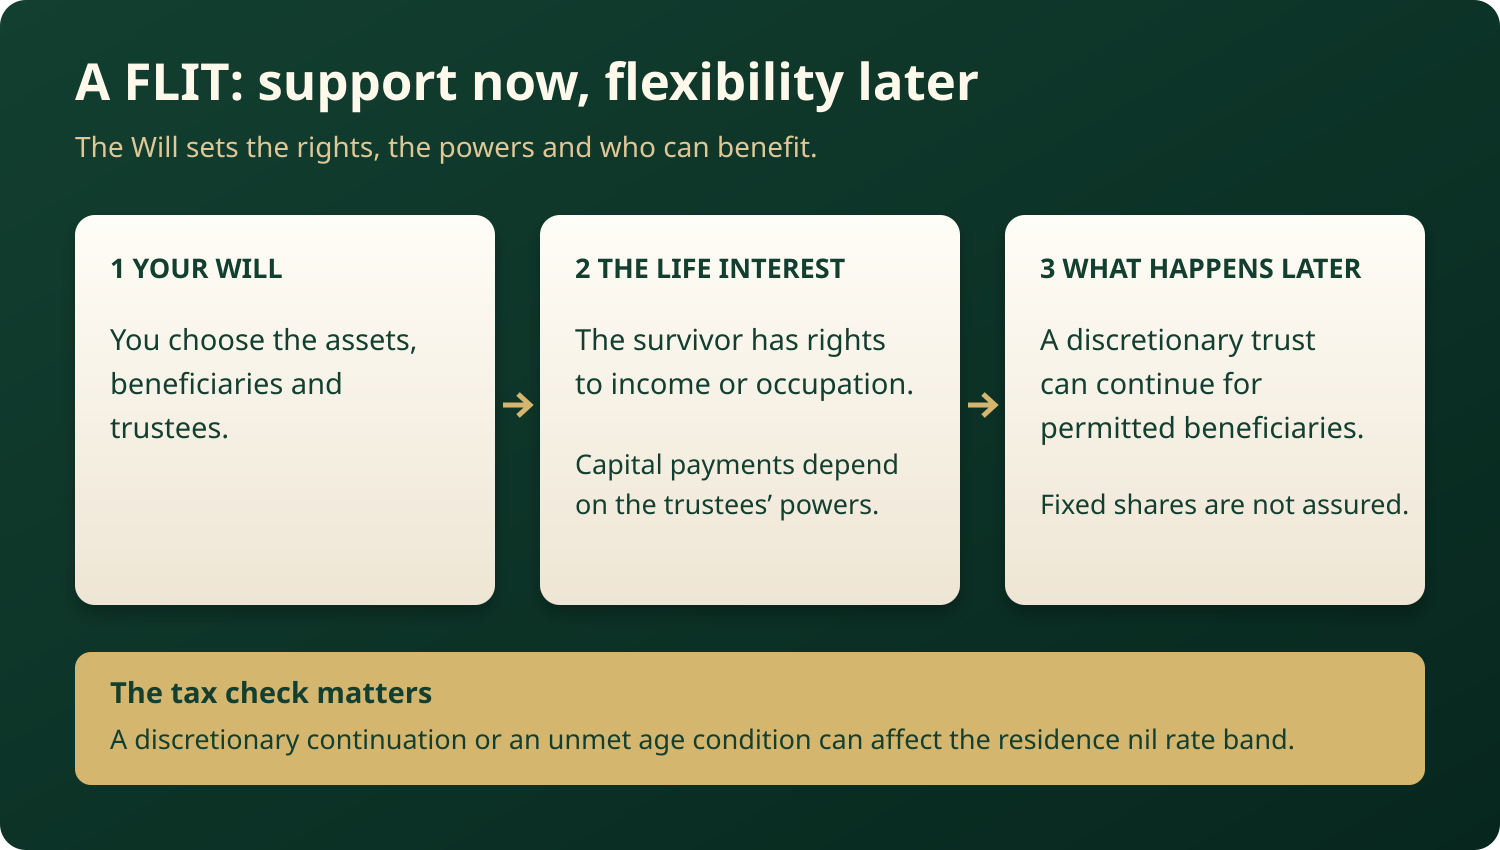
You decide what goes into the trust: for example, your share of the home, investments or the estate remaining after other gifts and expenses.
When you die, your chosen person becomes the “life tenant”. The Will sets out their rights and the trustees’ powers. An immediate qualifying life interest created by a Will is commonly called an “immediate post-death interest”, or IPDI.
During that person’s lifetime, trustees may be able to use capital as well as income, make loans or change how assets are held. These powers come from the Will. The name FLIT does not mean every trust has identical powers.
When the life interest ends, a FLIT commonly continues as a discretionary trust. Trustees then decide which of the permitted beneficiaries should benefit, when and how much. That can help where children have very different needs, but it gives them less certainty than a fixed inheritance.
A few useful terms
- Life tenant: the person with the current right to benefit, often the surviving spouse.
- Trustees: the people responsible for managing the trust and following its terms.
- Capital: the underlying assets or money, rather than the income they produce.
- Discretionary beneficiaries: people the trustees may help, without each having a fixed entitlement.
Andy and Beth: what flexibility looks like
These are illustrations, not descriptions of particular clients. Each outcome depends on the Will and the circumstances.
1. Keeping inheritance on track
Andy leaves everything outright to Beth. She later marries Charles. Depending on her later Will or the intestacy rules, wealth originally belonging to Andy could eventually pass to Charles or his family.
With a FLIT, Andy’s remaining trust assets stay governed by Andy’s trust terms. Beth cannot redirect them simply by changing her own Will. However, capital paid out to Beth becomes hers, and amounts used during her lifetime reduce what remains.
2. Helping Beth through a difficult period
After Andy’s death, Beth needs more than the trust income to meet her living costs. If the Will permits it, the trustees can consider releasing capital. They look at her needs, the size of the fund and the effect on everyone else who may benefit.
This is the practical value of flexibility: a plan can respond to real life without assuming that every payment is affordable or appropriate.
3. Helping the children earlier
The children would benefit from help with deposits or weddings. The trustees may be able to assist if they fall within the permitted beneficiaries and the relevant powers allow it.
Andy’s Letter of Wishes can explain his priorities. It guides the trustees; it does not give them powers missing from the Will. Significant payments need tax advice before they are made.
4. If Beth faces bankruptcy
Assets held in trust are different from assets Beth owns outright. That distinction can offer protection, but it is not a blanket shield from creditors. Her income rights, the trust terms and the circumstances all matter. The trustees should obtain advice before making payments or changing her rights.
5. If Beth needs residential care
If the trust terms allow, the trustees may be able to let the property and use the rental income to support Beth. The arrangement can help provide for her needs while retaining the property in trust.
Trust income and Beth’s own assets may still be relevant to a care assessment. A FLIT should not be presented as a guaranteed way to avoid care fees, and arrangements involving deliberate deprivation can be challenged.
6. If Beth wants to help Charles
Charles becomes ill and Beth asks the trustees to help with treatment costs. They must first establish whether the Will permits that use of the money. Beth’s request or Andy’s Letter of Wishes cannot, by itself, authorise a payment to someone outside the permitted arrangements.
The home and how it is owned
Where a jointly owned home is held as beneficial joint tenants, the deceased owner’s interest normally passes automatically to the survivor. The Will cannot direct that interest into a FLIT.
With tenants in common, each owner has a distinct share that can pass under their Will. The shares need not be equal. A solely owned property can also be left into trust.
Ownership should therefore be checked alongside the Will. Our guide to severance of tenancy explains the distinction.
The important inheritance-tax trade-off
A FLIT is primarily a way to control and support family inheritance. Tax savings are not automatic.
While a qualifying life interest continues, the trust assets are normally treated as part of the life tenant’s estate for inheritance tax. They are not generally subject to the ten-year charges that apply to discretionary trusts during that period.
Changing the life interest or distributing assets can have tax consequences. Paying capital to the life tenant is different from giving it to children or moving it into a discretionary arrangement. Loans also need careful advice; calling a payment a loan does not itself produce a tax saving.
If the trust continues on discretionary terms, ten-year and exit charges may apply. Their amount depends on the trust’s circumstances.
What about the residence nil rate band?
The residence nil rate band is an extra inheritance-tax allowance that can apply when a qualifying home passes to direct descendants, subject to the other eligibility rules.
Leaving a home into a qualifying life-interest trust for a spouse does not use this allowance on that death, although unused allowance may be transferable to the surviving spouse’s estate. An unmarried partner has no equivalent transfer entitlement.
Leaving the home in a life-interest trust for an unmarried partner will not normally qualify for this allowance on your death, because the partner is not your direct descendant. Naming children to inherit later does not change who benefits immediately.
When the surviving life tenant dies, the destination of the trust property matters. If it remains in a discretionary trust, naming children among the possible beneficiaries is not enough to secure the allowance for that property.
Nor should trustees assume that paying it to the children within two years of the survivor’s death will put matters right. The familiar two-year rule for some Will trusts does not provide that rescue for the earlier FLIT once a qualifying life interest has existed.
Age conditions need care too. If children or grandchildren must survive to 21 or 25 before becoming entitled after the life tenant’s death, an age condition still unmet at that death can prevent the allowance applying to the affected trust property. Different rules can apply to a gift made directly under a parent’s Will, so an inheritance age of 21 does not automatically mean the allowance is lost.
The practical lesson is to check the intended inheritance route when the Will is prepared and before trustees change it. Our residence nil rate band guide explains the allowance more broadly.
Costs and responsibilities after death
The executors and trustees must bring the trust into operation during estate administration. That includes identifying the assets, dealing with ownership and keeping proper records. A trust clause is not a substitute for those steps.
An ongoing FLIT will usually need Trust Registration Service registration once the relevant Will-trust exclusion ends. Tax liability can trigger registration earlier. Trustees also need to consider income tax, capital gains tax and reporting when relevant.
Professional help may be needed for registration, accounts, property transactions or significant decisions. Costs depend on the work involved and should be weighed against the benefit the trust provides. See Will trust costs and administration for more detail, and Services & Fees for current Fern pricing.
Choose trustees who can work together, keep records and make fair decisions. The survivor can be one trustee, but the choice of co-trustees matters, especially where different branches of a family have competing interests.
Can the survivor move home?
Often, yes, if the Will gives the necessary powers. Trustees will need to consider the replacement property, ownership, costs and tax before proceeding.
Can the survivor spend all the trust money?
Not simply because they are the life tenant. Their rights and the trustees’ powers depend on the Will. Broad capital powers can allow substantial distributions, so flexibility must be balanced against the inheritance you want to preserve.
Is a FLIT better than a property life interest trust?
It depends on your priorities. A simpler property life interest arrangement may suit a family wanting clearer eventual shares. A FLIT offers broader scope to respond to changing needs, with more trustee discretion and possible tax trade-offs. The detailed wording matters more than the label.
Can we change our minds?
While you are alive and have the necessary capacity, you can review and change your own Will. After your death, trustees must work within the powers available to them. Do not assume they can later rewrite the arrangement to achieve any outcome the family wants.
Finding the right balance for your family
Start with the people, rather than the name of the trust. Who should have security now? Who should benefit later? How much freedom should trustees have to change the balance? Fern Wills & LPAs drafts trusts that arise on death within Wills. We do not take trustee appointments or provide trust administration or registration services. We can usually offer general pointers and specialist introductions when a trust needs to be operated, but that later support is goodwill only, subject to availability and the rules and pricing then in force. You remain free to choose your own adviser.
Contact us to discuss your family’s priorities and whether a FLIT or a simpler arrangement would suit them. You do not need to choose a trust before speaking with us. This article provides general information for England and Wales. The right arrangement depends on your circumstances, the Will’s wording and the law at the relevant time.